I Asked ChatGPT How to Build Credit. Here's What It Got Right (And Wrong)
ChatGPT gave surprisingly solid advice on how to build credit — but the more I read its answer, the more I realized it was giving information, not guidance.

Written by TomoCredit ·
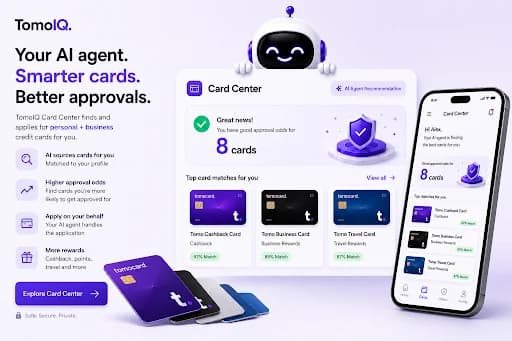
Meet TomoIQ
Your AI-powered credit assistant.
The Fed raised interest rates last week, which means it's time for everyone online to explain what this means for your money. Some of that advice is useful. Some of it makes you feel like you need an economics degree before you can open your credit card statement.
You don't.
If you're carrying a balance, the most useful thing you can do this week is find out what your card is charging you. A Fed rate change doesn't mean every credit card APR rises by the same amount on the same day. Your card's terms matter. But the announcement is a good reason to check a number many of us would rather avoid.
Open your latest statement and write down the balance, APR, and minimum payment for each card. "I owe around $3,000" can feel like one big, impossible problem. "I owe $2,000 at 27% and $1,000 at 18%" gives you something you can work with.
Before you decide which balance to attack, make sure you can pay every minimum on time. Set a reminder or turn on autopay for the minimum if that works for your cash flow. One missed payment can create a problem you didn't need.
The highest interest balance is often the place to put extra money if your goal is to reduce interest costs. But I don't want to give you advice that works beautifully on a spreadsheet and falls apart when rent is due. Look at the money you actually have available. An extra $30 you can pay consistently is a real plan.
Maybe your next step is checking when a promotional APR ends. Maybe it's calling your issuer to ask about your options. Maybe it's simply opening the statement today instead of spending another month guessing.
That last one counts, by the way.
When I was denied a car loan despite having a job as an investment banker, I learned how frustrating it is to have your financial life reduced to a decision that doesn't seem to reflect your reality. That experience is part of why I started TomoCredit. People deserve financial tools that help them understand where they stand and what they can do next.
It's also the idea behind TomoIQ: guidance that meets you where you are. If the question on your mind is "Which card should I pay first?" you should be able to start there. You don't need a perfect budget or a five-year financial plan before you're allowed to ask.
So ignore the pressure to make a dramatic money move because of one headline. Open one statement. Find your APR. Choose one step you can take this week.
That's a good start.
ChatGPT gave surprisingly solid advice on how to build credit — but the more I read its answer, the more I realized it was giving information, not guidance.
The most useful financial AI might be the one that helps you tackle the money task you've been avoiding. When life gets busy, managing money often falls to the bottom of your to-do list—but it doesn't have to be complicated.
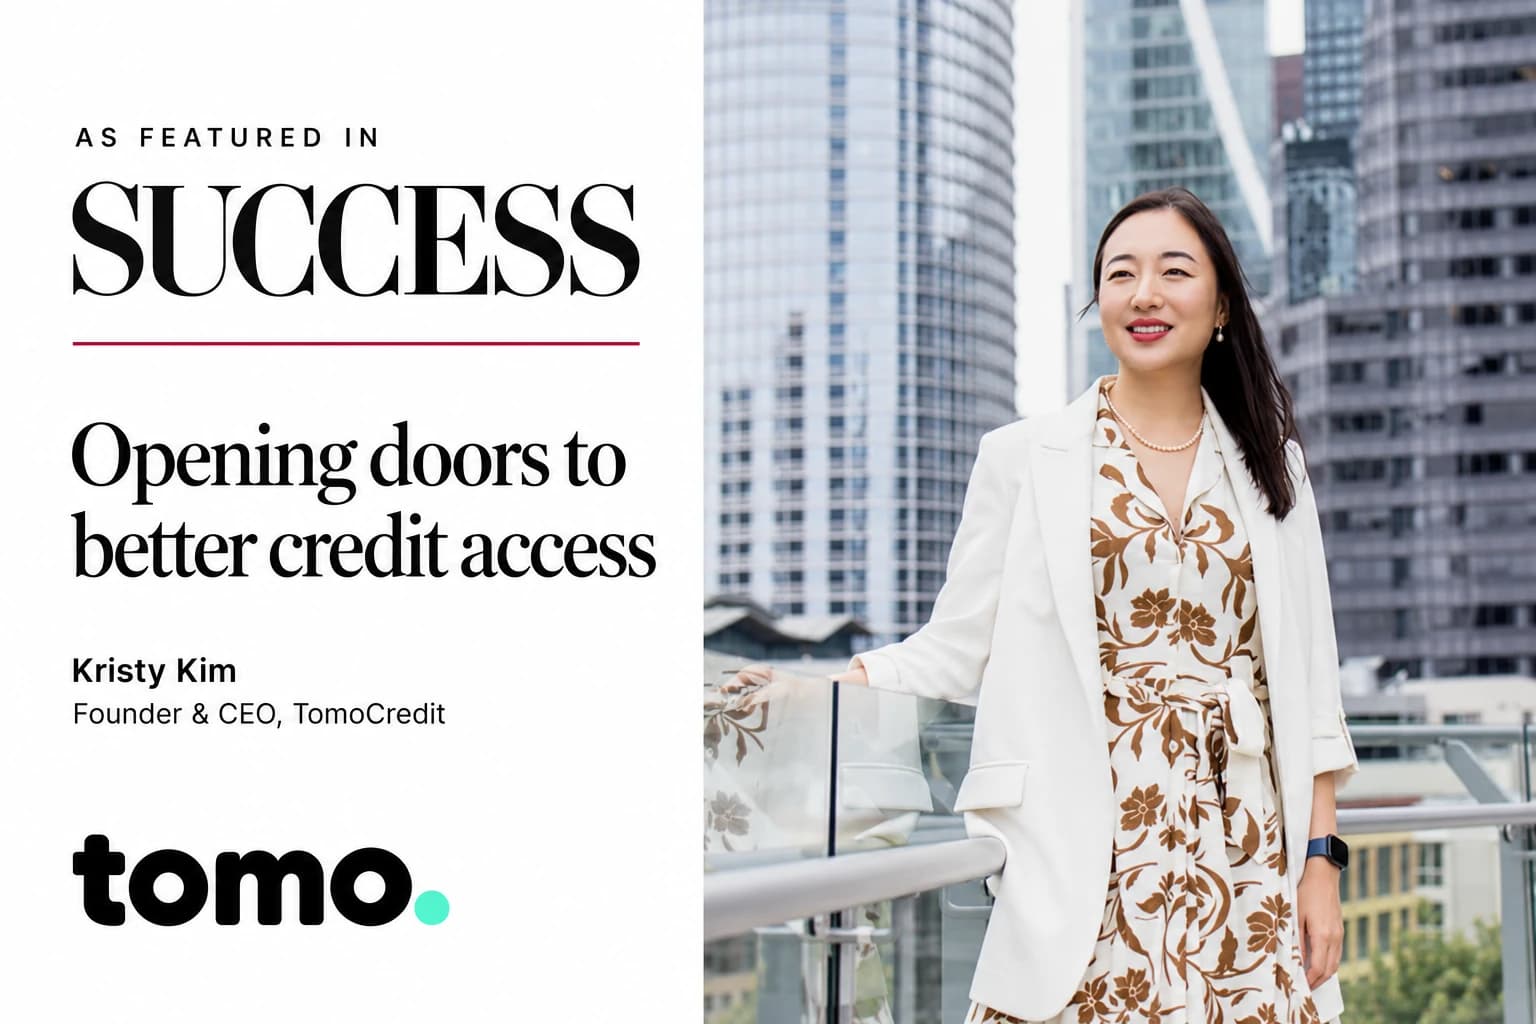
Founder and CEO Kristy Kim shares the personal experience that inspired TomoCredit in SUCCESS magazine, revealing how a credit rejection sparked a mission to expand financial access for everyday Americans.
The language used on this page is for creative purposes only. TomoCredit (or TomoBoost) does not guarantee an increase in credit score. Individual results vary based on each person's unique credit history and financial circumstances, and subscription payments are non-refundable.
Meet TomoIQ
Your AI-powered credit assistant.